Does Homeowners Insurance Cover Water Damage in Colorado?
By Boulder Water Dispatch · Reviewed
Short answer
Usually yes for sudden water from inside the house, like a burst pipe or a failed water heater. Usually no for sewer or sump backups unless you bought a water backup endorsement. Never for flooding from outside, which needs separate flood insurance.
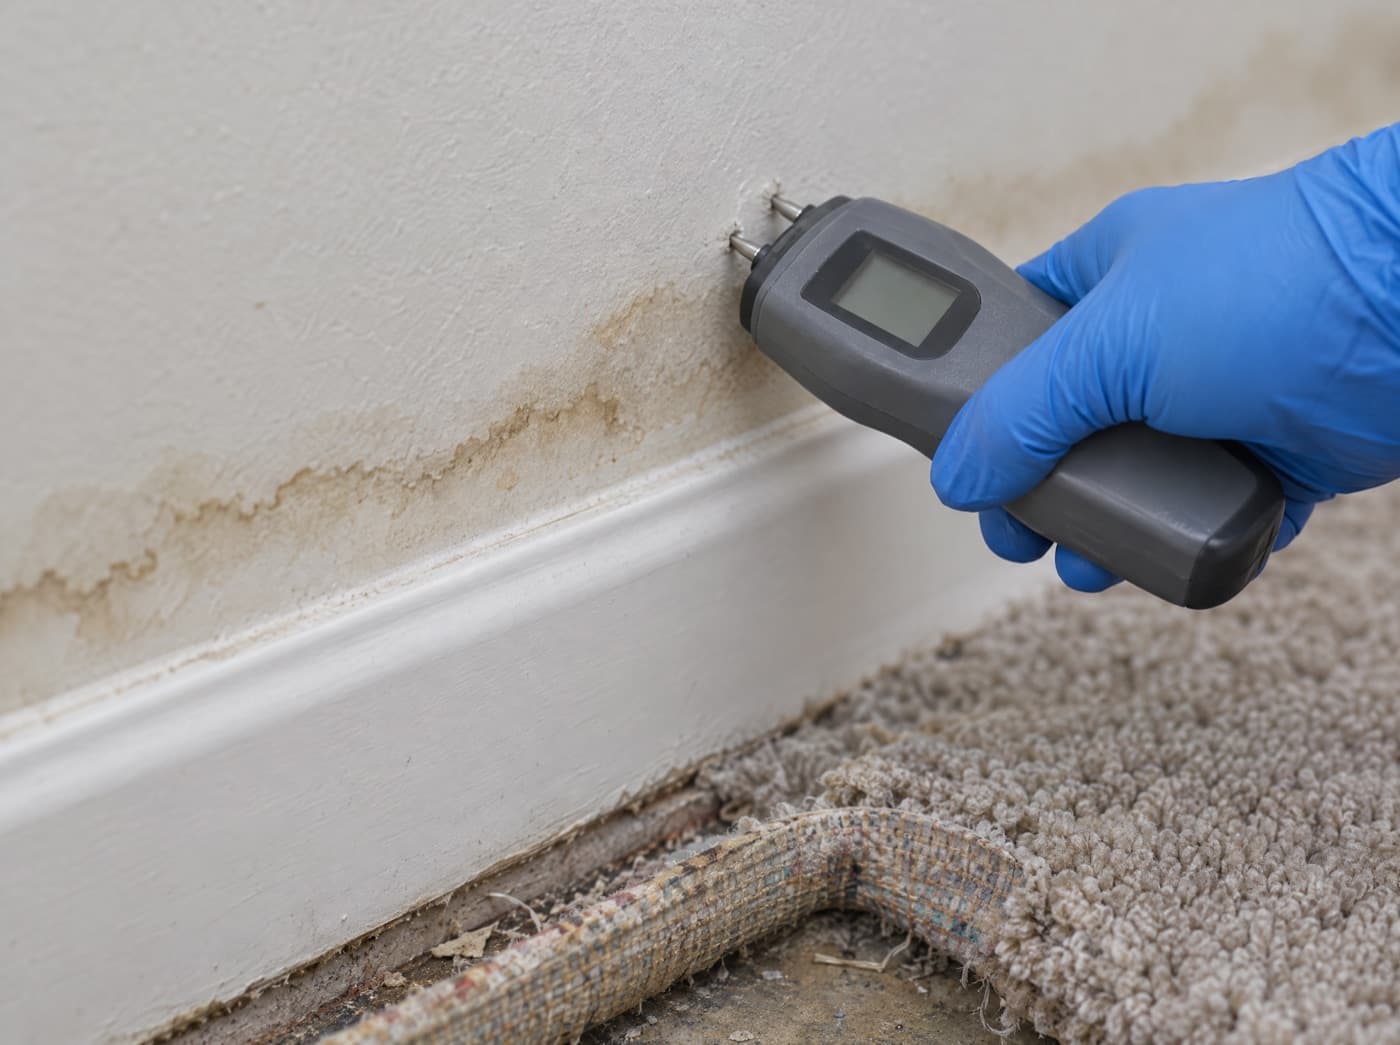
Most Colorado homeowners carry an HO-3 policy. Whether it pays for water damage depends less on how bad the damage looks and more on where the water came from. Here is how each common Boulder water loss is usually treated. Your own policy and adjuster have the final word.
Usually covered: sudden water from inside the house
HO-3 policies cover "sudden and accidental discharge" of water from plumbing, heating, air conditioning, and household appliances. That includes:
- A burst or frozen pipe, as long as the home was heated or the water was shut off and drained
- A water heater, washer hose, dishwasher, or fridge line that fails suddenly
- Drying, tear-out needed to reach the leak, and repairs of resulting damage
- Hotel or rental costs if the home can't be lived in
The broken pipe or appliance itself is usually not covered, and slow leaks that went on for weeks are commonly excluded as repeated seepage.
Needs an endorsement: sump pump and sewer backups
Water that backs up through a drain or overflows a sump pit is excluded from the base HO-3 form. It's covered only if you added a water backup endorsement, which often has its own limit, commonly $5,000 to $25,000. Look for "water backup" on your declarations page. See basement flood cleanup and sewage backup cleanup for what those jobs involve.
Needs flood insurance: water from outside
Overland flooding, flash floods, and creek overflow are excluded from every standard homeowners policy. They are covered only by a National Flood Insurance Program (NFIP) policy or a private flood policy. NFIP building coverage goes up to $250,000 and contents up to $100,000, and new policies generally take effect after 30 days. Flash floods can reach homes well outside mapped floodplains, so it's worth checking your flood zone at the FEMA Flood Map Service Center even if you aren't near a creek.
Your rights as a Colorado policyholder
- You can ask your insurer for a complete copy of your policy, including the declarations page and endorsements, and it must be provided within three business days of your request. (Colorado HB13-1225 (Homeowner's Insurance Reform Act))
- You can request a certified copy of your policy, which the insurer must make available within thirty days. (C.R.S. 10-4-110.8)
- If you disagree with how a claim was handled, you can file a complaint or ask questions with the Colorado Division of Insurance. (Colorado Division of Insurance)
How to file a water damage claim
- Stop the water: close the main shutoff, and switch off power to wet rooms only if it's safe.
- Photograph every wet room from all four corners, plus close-ups of the source and damaged items.
- Call a restoration company to start drying. Policies expect you to prevent further damage.
- Call your insurer or agent, report the loss, and write down the claim number.
- Keep receipts for anything you spend, including hotel stays and emergency supplies.
- Give your adjuster the moisture readings, photos, and itemized estimate from the restoration company.
Want a quick read on your situation first? The free damage estimator shows the water category, typical equipment, and the likely insurance outlook in about a minute. For what a job costs and what you pay out of pocket, read our water damage restoration cost guide.
This guide is general information, not insurance or legal advice. Policies differ; read yours and talk to your agent.
Common questions
Will my insurance rate go up if I file a water damage claim?
It can. Insurers look at claim history when they renew or price a policy, and water claims get extra attention. That's a reason to talk with your agent about the size of the loss compared to your deductible, not a reason to skip drying. Unchecked water damage gets more expensive every day.
Does homeowners insurance cover mold?
Many policies limit or exclude mold, but they usually cover the water damage that caused it if the water loss itself is covered and you acted promptly. Fast drying and good documentation keep a water claim from turning into a mold claim with a lower limit.
I rent. Who pays for water damage?
The building is the landlord's responsibility and their insurance. Your renters policy (HO-4) may cover your belongings and temporary housing if the loss is a covered peril. Tell your landlord in writing right away.
I own a condo. Is the HOA or my policy responsible?
It depends on your HOA's master policy and bylaws. The master policy often covers common areas and the building structure, while your HO-6 policy covers your unit's interior and belongings. Read both before you call either insurer.